E-Wallet App Development Cost: Factors, Hidden Costs, and Estimates
Updated 16 Oct 2026
18 Min
129 Views
An e-wallet budget depends less on features than on what surrounds it: licensing and compliance in every market, integrations with banks and payment gateways, security certification, and infrastructure sized for transaction load. If you plan only for development, these items surface as unplanned costs and push your final bill above the first estimate.
For 15+ years, we at Cleveroad have delivered FinTech software with payment flows at its core, from micro-investment apps to eBanking platforms and multi-currency e-wallets. In this guide, we break down the factors that shape e-wallet app development cost, the hidden costs outside development, the cost split by development stage, overall estimates by complexity, and practical ways to reduce your budget.
Key takeaways:
- E-wallet costs range from $30,000–$50,000 for basic apps to $50,000–$100,000 for mid-range solutions and $100,000–$250,000+ for full platforms..
- Cross-platform development cuts mobile development costs roughly in half compared to two native apps.
- The costs founders miss sit outside development: compliance, cloud infrastructure, store publishing, and monthly support.
What Is an E-Wallet App and Why Is It Popular?
An e-wallet app is a mobile application that securely stores users’ payment data, such as card and bank account details, and lets them pay and transfer money from one place. It replaces physical credit, debit, and loyalty cards both at checkout and online.
Users can link their payment cards and bank accounts to the e-wallet app. This allows them to make payments for services such as online shopping, utility bills, and peer-to-peer transfers without needing to physically carry their cards or enter their financial information every time. The listed operations are possible through the following constituents of the mobile wallet:
- Near Field Communication (NFC) technology enables two devices to exchange information when in close proximity, and is used by both Apple Pay and Google Pay. The merchant must have compatible card readers at checkout to use one of these digital wallets.
- Magnetic Secure Transmission (MST) was previously used in Samsung Pay to emulate swipes from magnetic stripe cards. However, its use is now deprecated in new models, as NFC has become the new standard. Most banks and terminals are increasingly adopting NFC due to its enhanced security and wider acceptance.
- QR codes, which are scannable barcodes, can be read with a smartphone's camera. Some apps allow customers to generate a QR code to be used to make payments at stores.
To protect payments, current e-wallets implement end-to-end encryption, tokenization, and multi-factor authentication. Fingerprint or face recognition and the use of PIN or passcodes introduce a further level of security. The diagram below shows how these components work together in a single e-wallet payment flow.
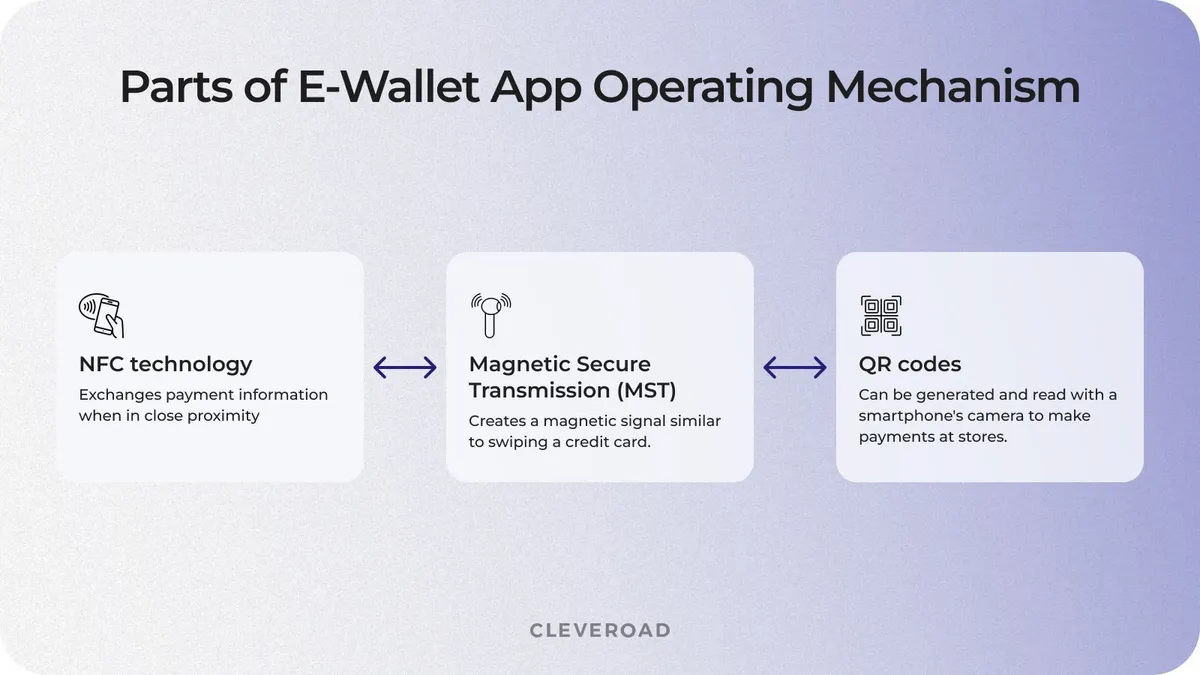
Components of an e-wallet payment mechanism: NFC, QR codes, tokenization, and authentication
Why are mobile wallets popular?
The e-wallet market keeps growing at a fast pace. According to Market Research Future, the market was valued at $124.6 billion in 2024 and is projected to reach $1,120.65 billion by 2035, growing at a compound annual growth rate (CAGR) of 22.1% over 2025–2035.
Two trends drive this growth. The GSMA Mobile Economy 2026 report shows that 4.7 billion people, or 58% of the global population, now access the internet through their own mobile devices. Meanwhile, Capgemini’s World Payments Report 2026, as announced in the company’s press release, estimates that global non-cash transactions passed 1.6 trillion in 2024 and will exceed 3.5 trillion by 2029. Digital wallets and instant payments together grew from 13% of the global payment mix in 2020 to 25% in 2024.
As demand grows, more founders ask what it takes to build an e-wallet and how much to budget for it. The answer starts with the factors that shape the development budget.
Factors Affecting eWallet App Development Cost
Each one moves your e-wallet app development budget in its own way, so knowing them upfront shows you where the money goes and where you can save.
E-wallet app complexity
Complexity defines your feature scope and, with it, most of the development hours behind your e-wallet cost. We group e-wallets into three tiers: simple, medium, and complex, where each tier adds features on top of the previous one.
You will find the features and cost range of each tier in the Overall eWallet App Development Cost section below, where all three tiers sit side by side in one table. Baseline security, such as biometric login and encryption, belongs in every tier, not only the complex one.
Platform selection
The choice of platform is another factor you should pay attention to while estimating the cost of mobile wallet app development. Each platform has its own design guidelines and security requirements, so every extra platform adds development and testing effort.
The tier ranges in this article assume one cross-platform app for iOS and Android. Here is how the other options compare:
- Native development (iOS & Android). This option provides the richest user experience and full access to device features, but requires separate codebases for each platform. Expect up to about twice the client-side development cost of a cross-platform app in the same tier, since every screen is built and tested twice.
- Web platform development offers a versatile and accessible option for creating an e-wallet application. It also allows for quicker updates and easier maintenance. A web-only e-wallet usually sits at the lower end of its tier’s range, which makes it a fit if you need to balance cost and functionality.
- Cross-platform development uses frameworks like React Native or Flutter (see our Flutter app development services) to create a single codebase that functions on both iOS and Android. This is the baseline behind the tier prices in the Overall eWallet App Development Cost section.
Types of e-wallets
The wallet type sets how much banking integration and regulation you take on, which is why prices below run from $15,000 for a closed wallet to $100,000+ for an open one.
Here is how the most common types of eWallet applications compare in features and development cost:
| Type of e-wallet | Cost-forming peculiarities | Estimated development cost ($) |
|---|---|---|
Closed wallets | Limited for use within a single vendor’s ecosystem. No need for banking or third-party integrations. Often built as a module inside an existing app, which is why it can cost less than a standalone simple e-wallet. | $15,000-$25,000+ |
Semi-closed wallets | Usable at multiple merchants via agreements. Requires integration with payment gateways and basic Know Your Customer (KYC) compliance. | $25,000-$45,000+ |
Open wallets | Supports full financial operations like ATM withdrawals and bank transfers. Requires deep banking system integration and regulatory compliance. | $60,000-$100,000+ |
Crypto wallets | Stores and transfers cryptocurrencies. Requires blockchain integration, encryption protocols, and real-time syncing. | $50,000-$90,000+ |
Super apps (wallet core) | Combines e-wallet functionality with additional services (e.g., ride-hailing, food delivery, utility payments). Requires microservice architecture and extensive UX logic. The range covers the wallet core only; ride-hailing, food delivery, and other services are priced as separate projects. | $100,000-$200,000+ |
Ranges are based on Cleveroad's delivery data from shipped FinTech products and calculated at Central and Eastern European engineering rates as of October 2026. With North American or Western European rates, each range moves higher.
Security protocols and features
Security adds a set of costs you can’t trim from the eWallet cost. For financial services or bank app integrations, security certifications such as PCI DSS are frequently required and take extra development time and skills.
Typical security costs for an e-wallet:
- Tokenization mechanisms: $4,000–$8,000+
- PCI DSS certification preparation: $25,000+
- End-to-end encryption: $5,000–$10,000+
- Biometric authentication: $6,000–$12,000+
Budget for these items at the architecture stage. Adding tokenization or PCI DSS controls after launch usually means reworking the payment flow and repeating security testing, which costs more than building them in from the first sprint.
The $25,000+ PCI DSS figure applies when your app stores or processes card numbers itself. If a processor such as Stripe or Adyen captures and tokenizes the card, your PCI scope often shrinks to a short self-assessment questionnaire (SAQ A) instead of a full audit.
Feature set and integrations
The table below groups e-wallet features by category, with cost ranges from Cleveroad’s FinTech Solution Architects.
| E-wallet feature category | Focus | Estimated cost range ($) |
|---|---|---|
Core features | Essential payments: KYC, login, balance, transfers, transaction history | $10,000-$25,000+ |
User experience | Smart tools: budgeting, bill reminders, multi-currency, loyalty sync | $20,000-$45,000+ |
AI & security | Fraud prevention, biometrics, spend analysis, predictive suggestions | $30,000-$70,000+ |
Integrations | APIs for banks, crypto wallets, Buy Now, Pay Later (BNPL), third-party services | $10,000-$80,000+ |
Advanced add-ons | Super app features: investing, insurance, voice AI, marketplaces | $50,000-$120,000+ |
Ranges were compiled by Cleveroad's FinTech Solution Architects from shipped e-wallet and payment products, at Central and Eastern European engineering rates as of October 2026.
Use this table as a starting point for your feature list. Integrations carry the widest range because one bank API costs far less than a multi-bank, multi-currency setup, so confirm your integration list with a FinTech vendor before you lock the budget.
If you want to know more about advanced e-wallet app features you can implement with Gen AI in FinTech, read our recent article.
Technology stack
Two stack choices move the budget most. Managed cloud services, such as a managed database or authentication service, replace custom infrastructure work with a predictable monthly fee, while a payment processor’s SDK that tokenizes cards on its side keeps your app out of full PCI DSS scope. The image below shows the technology stack IT experts at Cleveroad typically use when developing FinTech apps like mobile wallets:
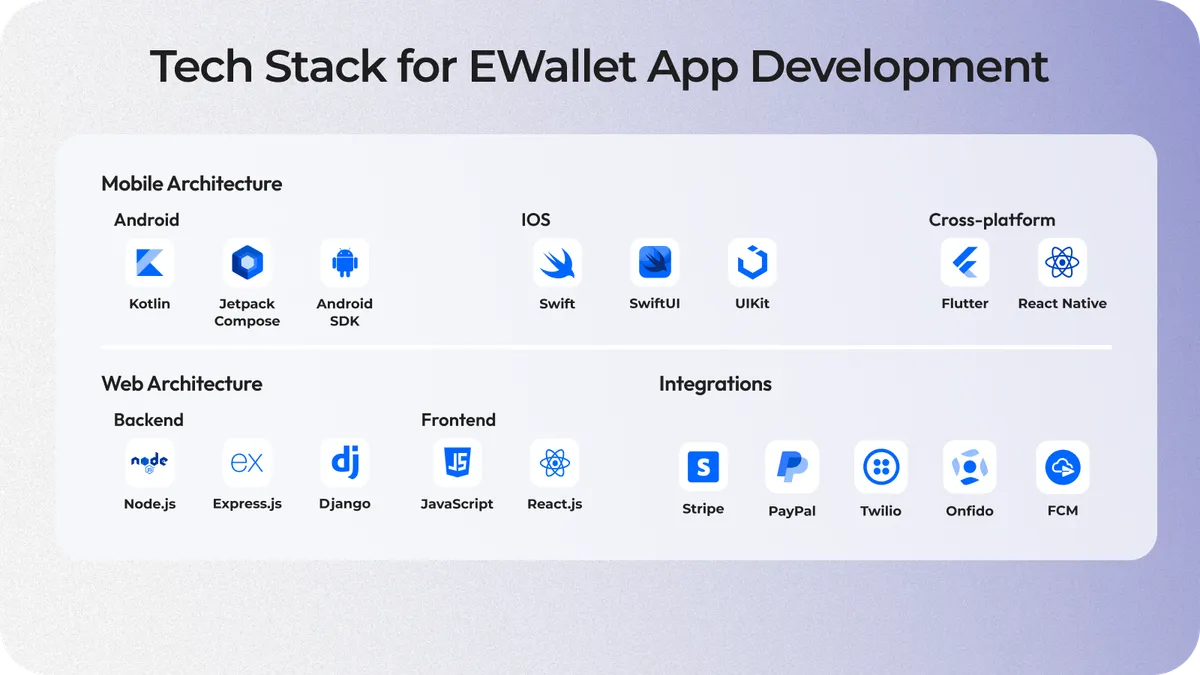
Cleveroad tech stack for e-wallet creation
IT vendor’s location
FinTech software development vendors in different regions offer varying costs for their services due to differences in the cost of living, labor market conditions, and economic factors. Here's a breakdown of estimated nearshore and offshore e-wallet app development cost:
- Nearshore development. Typically located in neighboring countries or regions with similar time zones. Hourly rates for nearshore software development can range from $50 to $100+ per hour, offering a good balance between cost and communication ease.
- Offshore development. Located in countries farther away with significant cost of living differences. Rates can range from $20 to $50+ per hour, but factors like time zone differences and potential language barriers require careful consideration.
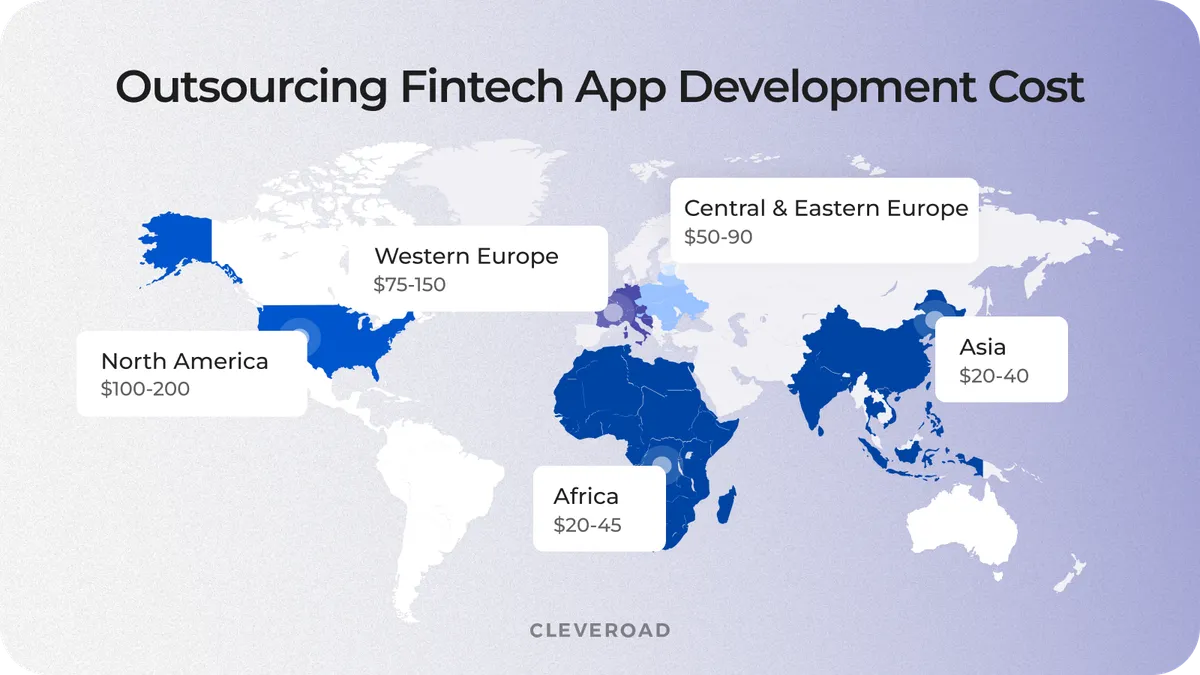
Outsourcing e-wallet app development cost for different regions
For instance, if you're based in New York, nearshore e-wallet development partners could be found in countries like Canada or Mexico, offering similar time zones and strong technical talent at a more competitive rate. On the other hand, offshore software development teams in Central and Eastern Europe like Estonia or Poland can provide highly skilled developers at even more cost-effective rates.
A lower e-wallet app development cost may come with trade-offs such as time zone differences and communication gaps. Skilled FinTech vendors handle them with structured project management and clear, consistent communication, so your solution still ships on time and at the expected quality.
Hidden Costs of E-Wallet App Building
Hidden costs are the expenses that sit outside the development estimate: compliance, infrastructure, store publishing, and post-launch support. They often stay out of a first development quote, yet they recur every month or year after launch, so plan them into your e-wallet app development cost from day one.
Regulatory compliance
Each country may have specific requirements for e-wallet app data security, protocols like Anti-Money Laundering (AML) and KYC, and even user authentication methods, which calls for additional development effort and legal consultations in each of your target markets.
On top of legal advice, many markets also require certifications. The cost of implementing these measures can escalate with continuous updates to regulations, and non-compliance can lead to hefty fines and legal disputes.
The largest compliance cost is the license to hold customer money. In the EU, an Electronic Money Institution (EMI) license requires €350,000 in initial capital; in the US, you need a money transmitter license in most states you operate in. Most early-stage wallets skip both by partnering with a licensed Banking-as-a-Service (BaaS) or e-money provider and paying per account or per transaction instead.
Here's a breakdown of the eWallet app development cost associated with regulatory compliance:
- Legal consultations cost $5,000–$20,000+, depending on the complexity of regulations and number of markets
- Certifications cost about $2,000–$10,000+, depending on the certification required. This covers market-specific certifications and basic PCI DSS self-assessments. Full PCI DSS compliance for apps that store card data costs $25,000+ separately.
- Compliance audits and regulatory updates cost $5,000–$15,000+ per year
Infrastructure and hosting
Your monthly cloud bill depends on how many users and transactions your e-wallet handles. The table below compares a lean setup at launch with a production setup scaled for growing transaction volumes, so you can plan the e-wallet cost of infrastructure for your first year and for the growth stage.
| Cost component | What it covers | At launch, per month ($) | At scale, per month ($) |
|---|---|---|---|
Cloud hosting | Servers, managed database, storage, and load balancing on AWS, Azure, or Google Cloud | $500-$3,000 | $2,500-$16,000+ |
CDN and security services | Content delivery network, firewalls, DDoS protection, and real-time monitoring | $400-$2,500 | $500-$3,000+ |
Backup and disaster recovery | Data backups and recovery planning that keep the business running during outages | $300-$1,500 | $1,000-$5,000+ |
Total | — | $1,200-$7,000 | $4,000-$24,000+ |
Estimates use AWS, Azure, and Google Cloud rates as of October 2026. Launch assumes ~10,000 monthly users in one region; scale assumes 100,000+ across regions. SSL adds $100–$500/year. Prices may vary.
Cleveroad is an AWS Select Tier Partner. Our DevOps team matches your cloud setup to expected load and compliance needs, so you pay for launch-level capacity first and scale later.
App publishing
Whether you’re aiming to publish your eWallet app in the Apple App Store or Google Play, you should consider that both marketplaces have their own fees, rules, and regular update requirements. It means you’ll be budgeting for more than just a one-time upload. Think about things like localization, App Store Optimization (ASO), and keeping your app compliant so it stays live and visible to users.
Here’s what usually affects the overall cost of eWallet publishing:
- App developer accounts: $99 per year for App Store and $25 one-time fee for Google Play
- App Store Optimization (ASO): $1,000–$5,000+. The price covers keyword research, optimizing metadata, visuals, etc.
- Localization and translation: $500–$5,000+. The cost increase depends on where you're launching and what languages you need.
- Store policy compliance checks: $1,500–$7,000/year, covering review-guideline changes and required SDK updates.
Apple also requires apps in banking and financial services to be submitted by the legal entity that provides the services, not by an individual developer (App Store Review Guideline 5.1.1(ix)). In practice, that means an organization developer account, which requires a D-U-N-S number for your company, so request it well before launch.
So when you’re planning the cost to build your app, don’t forget these extras. Because your app handles money, also include payment processing fees in your calculations: Stripe’s standard US rate, for example, is 2.9% + 30¢ per successful domestic card transaction. All this will help you accurately estimate the cost of getting your product live.
User support and maintenance
After launch, your e-wallet needs a support team that answers user questions and escalates bugs to developers. Round-the-clock coverage costs the most because it requires shifts across time zones.
User support, from a basic help desk to a 24/7 team, can range from $1,000 to $10,000+ per month, depending on the chosen support plan and the size of your support team. Code maintenance is budgeted separately as a share of your development cost, which we cover in the stages section below.
Running costs start on launch day: plan $1,200–$7,000 per month for hosting, 15–20% of your development cost per year for code maintenance, and a separate budget for user support, all on top of the development estimate.
E-Wallet App Development Cost by Development Stage
When you work with an outsourcing vendor, your e-wallet budget is spent stage by stage, from discovery to launch. Here is what each stage typically costs.
Cost of discovery phase in e-wallet app development
The Discovery phase services involve gathering information, analyzing requirements, and defining the mobile wallet project scope. This phase typically lasts one to three weeks, and to determine its approximate costs, you can multiply the total hours worked by the specialist's hourly rate. The estimated cost can vary from $1,600 to $4,800 or more.
Discovery is also where your estimate takes shape. Cleveroad specialists prepare a rough estimate during this phase, and the detailed estimate follows sprint by sprint once development starts.
- A rough eWallet app development cost estimate is provided to clients to give an overview of expected expenses and development stages. This process involves two rounds of revisions, with the initial estimate created following a Solution Workshop and a second one after the Discovery Phase.
- A detailed estimate is prepared before development begins. Developers take the documentation and requirements gathered in the Discovery Phase and estimate the specific scope of each upcoming sprint or two, which supports detailed sprint planning.
Price of UI/UX design in e-wallet app development
User interface and user experience (UI/UX) designers focus on developing user-friendly interfaces for mobile wallets to enhance user interaction. The UI/UX design in digital wallet applications can cost from $5,000 to $50,000 or more, depending on app complexity and customization depth.
Cost of e-wallet app development and QA
Frameworks and libraries for e-wallet development can be either open-source (free) or come with licensing fees. You can also source some e-wallet components, such as KYC checks, from third-party providers instead of building them from scratch.
For a minimum viable product (MVP), the eWallet app development cost starts with team time: an MVP with basic functionality takes about three months and roughly 1,000 hours of work, shared by FinTech developers, a business analyst or project manager, and a QA engineer. At an offshore rate of about $30 per hour, that comes to $30,000+ for the whole MVP.
Rigorous QA testing is also essential for a secure and stable e-wallet app. QA services typically range from $5,000 to $20,000+, depending on the complexity of the app and the scope of testing required.
Find out how to build a secure mobile wallet app from our article
Maintenance and support cost for e-wallet app
Plan two separate budget lines for life after launch. Code maintenance, which covers bug fixes, OS and library updates, and security patches, usually takes 15–20% of your initial development cost per year, or about $4,500–$10,000 for a simple wallet.
User support is a separate line: the $1,000 to $10,000+ per month from the hidden costs section pays for support staff and plans up to a 24/7 team, so it grows with your user base rather than your codebase. To keep both predictable, our clients often extend their Cleveroad team into post-release support through IT staff augmentation services.
With every stage covered, here is how your overall e-wallet app development cost usually splits across them:
| eWallet development stage | Share of total cost (%) |
|---|---|
Planning and research | 5% |
UI/UX design | 15% |
Front-end development | 20% |
Backend development | 25% |
API integration | 12% |
Testing and Quality Assurance | 18% |
Deployment and launch | 5% |
Total | 100% |
Shares reflect the average budget split across Cleveroad's FinTech deliveries of comparable scope, as of October 2026.
Post-launch maintenance sits outside this split: plan another 15–20% of your development cost per year, as described in the maintenance section above.
Overall eWallet App Development Cost
Your development budget comes from the cost factors covered earlier: complexity, platform, wallet type, security, and integrations. Matching your idea to one of three complexity tiers gives you a realistic range before you talk to a vendor. These tiers cover development only, so add the hidden costs described in the Hidden Costs of E-Wallet App Building section, such as compliance and monthly hosting, on top. Here is the average e-wallet app cost by complexity, with the feature scope each tier usually covers:
| E-wallet app complexity | Description | Approximate development cost ($) |
|---|---|---|
Simple e-wallet application | Offers core functionalities like P2P transfers, bill payments, and top-ups from linked bank accounts, with baseline security such as biometric login and encryption | $30,000-$50,000 |
Medium e-wallet application | Adds in-app purchases, multi-currency support, and budgeting tools to the simple tier | $50,000-$100,000 |
Complex e-wallet application | Adds loyalty programs, investment options, AI-powered financial tools, and advanced fraud prevention to the medium tier | $100,000-$250,000+ |
Ranges are based on Cleveroad's delivery data from shipped FinTech products, including e-wallets, payment platforms, micro-investment apps, and eBanking systems, calculated at Central and Eastern European engineering rates as of October 2026.
These ranges are a starting point: two apps in the same tier can differ widely once you add specific integrations or target markets. To obtain the detailed cost estimate for your e-wallet application, you can directly contact a FinTech app development partner. We can help refine this estimate based on the specific features you envision.
Expert Tips to Reduce the eWallet Cost for Your Business
The tips below cut the costs that grow fastest in an e-wallet budget: feature scope, platform work, testing, and team rates.
Prioritize features
Every feature beyond payments and transfers adds development hours and often a new integration or compliance check, so your first release should cover only what users need to move money.
Cleveroad tip: Launch a closed-loop wallet first, where users top up and spend within your own ecosystem, and add open-wallet features such as bank transfers and cash withdrawals once you have a licensing partner. This keeps your first release clear of the heaviest integration and compliance costs.
Consider cross-platform development
Developing separate apps for Android and iOS can double your development workload and resources. This not only extends the time to market as well as e-wallet app development cost, but also makes ongoing maintenance and updates a complex affair.
Cleveroad tip: If you go cross-platform with Flutter or React Native, budget for native modules anyway. NFC tap-to-pay and in-app card provisioning to Apple Pay and Google Pay rely on platform-specific APIs, so plan them as separate iOS and Android work from the start rather than discovering them mid-project.
We used this approach for Rowing Australia’s Row Nation app, building one Flutter codebase for iOS and Android with Bluetooth connections to rowing machines and heart-rate monitors that work the same on both platforms.
Georgia Beattie, Director at Rowing Australia, on Successful Partnership with Cleveroad
Automate testing and use cloud services
Manual testing drives up the cost of developing an e-wallet, and the effort grows with every release as your app scales. On top of that, using traditional infrastructure usually means big upfront costs, which pushes up the final cost and makes the eWallet app harder to scale.
Cleveroad tip: Our QA engineers automate regression testing to catch bugs faster and cut down on human mistakes, keeping your iOS and Android apps stable between releases. Plus, we use cloud platforms like AWS or Azure that let you scale your backend smartly while you create an eWallet application for your business.
Outsource e-wallet app development
In-house development gives you full control over the process and intellectual property, but it pays off mainly when you can fund a full FinTech team for years. If you are a startup or work with a fixed budget, outsourcing usually costs less.
Cleveroad tip: Outsource to FinTech developers in regions with competitive rates, but check the vendor before you sign. Ask for shipped e-wallet or payment products, proof of PCI DSS and KYC/AML work, and at least four hours of daily time-zone overlap with your team.
Compared with the offshore rates in the IT vendor’s location section, the gap is widest between North America and Central and Eastern Europe (CEE). According to the U.S. Bureau of Labor Statistics, a US software developer earned a median of $135,980 a year in May 2025, or about $65 per hour before benefits and overhead, while offshore rates start at $20–$50+ per hour. FinTech developers in CEE countries such as Estonia or Poland charge lower hourly rates for comparable experience, which is why outsourcing there usually costs you less than building an in-house team.
Cleveroad Expertise in E-Wallet App Development
Cleveroad is a FinTech software development company with 15+ years of hands-on experience in the domain. We help financial institutions automate workflows and strengthen transaction security with custom FinTech software, e-wallet applications included. Our solutions rely on integrations and tools such as Salesforce, Abra, PayPal, Mastercard, NFC, and blockchain.
Working with us, you can receive the following benefits:
- Partnering with a trusted FinTech IT company, certified with ISO 9001 and ISO 27001 for quality systems and security management
- Free Solution Workshop stage to clarify your FinTech business issues and offer a proper technical solution for your e-wallet application
- Signing the NDA to protect the uniqueness of your mobile wallet concept per your request
- On-demand FinTech software development services: creating mobile wallets from scratch, software modernization, UI/UX design services, and IT consulting
- Project Management Office making sure that work on your e-wallet creation meets all your goals, on time and on budget
- AI-assisted and AI-native development teams that use AI tools for coding, testing, and documentation to speed up e-wallet delivery and help optimize your development budget
FinTech projects behind the estimates
The cost ranges in this article come from FinTech products we have delivered. Here are two from our portfolio, with the timelines and team setups that stand behind the numbers.
- Micro-investment platform for the Middle East market
A Saudi Arabian investment company operating since 1988 wanted to enter micro-investing with a mobile platform that met the requirements of the Saudi Central Bank (SAMA). Our team of 8 specialists built a cross-platform app with multi-factor authentication, KYC verification with liveness detection, and real-time stock rates. A separate web admin panel lets the client’s staff run the back office. The platform went from discovery to release in 7 months, passed regulatory assessment, and is compatible with the SAMA Cybersecurity Framework.
- eBanking ecosystem for a Swiss investment bank
A Swiss investment bank serving B2B and B2C clients needed to replace its outdated MVP with a system that could scale with its client base and speed up account opening under its existing license. Three Cleveroad teams (20 specialists in total) each took one sub-project. Together, they built a step-by-step sign-up flow, digital account opening with three KYC verification routes, a role-based tool for bank operators, and an online banking portal. The whole system complies with the Financial Market Infrastructure Act (FMIA). After launch, user retention improved by 20–30%, and the bank now operates freely under its license.
Build your e-wallet with FinTech experts
Our FinTech experts will build a secure e-wallet with seamless bank integrations, scalable architecture, and a development approach that fits your budget
The cost to build an eWallet usually starts at around $30,000 for a basic MVP, while advanced, feature-packed eWallet solutions run $100,000–$250,000+. The cost of building depends on how complex the app is, what tech stack you choose, the level of security you need, and what gets added in during the app development process.
Beyond feature scope, the wallet type moves the price most, because it defines how much banking integration and regulation you take on. Expect the following development ranges:
- Closed wallet: $15,000–$25,000+
- Semi-closed wallet: $25,000–$45,000+
- Crypto wallet: $50,000–$90,000+
- Open wallet: $60,000–$100,000+
- Super app (wallet core only): $100,000–$200,000+
The UI/UX design in digital wallet applications can cost from $5,000 to $50,000 or more, depending on app complexity and customization depth.
Four moves cut the budget most:
- Launch with core features only: KYC, login, balance, transfers, and transaction history fit into a $10,000–$25,000+ core set.
- Build one cross-platform app with Flutter or React Native instead of two native apps, which roughly halves mobile development costs.
- Outsource to an offshore vendor in Central and Eastern Europe, such as Estonia or Poland, instead of hiring an in-house team.
- Partner with a licensed Banking-as-a-Service (BaaS) or e-money provider instead of getting your own e-money or money transmitter license.
Evgeniy Altynpara is a CTO and member of the Forbes Councils’ community of tech professionals. He is an expert in software development and technological entrepreneurship and has 10+years of experience in digital transformation consulting in Healthcare, FinTech, Supply Chain and Logistics
Give us your impressions about this article
Give us your impressions about this article